Quick answer: If you set his hours, hand him your tools and tell him how to do the job, he's an employee in the eyes of the IRS, whatever form you had him sign. Pay him on a W-2, carry workers' comp, and treat "apprentice" as an employee with a training plan, not a loophole.
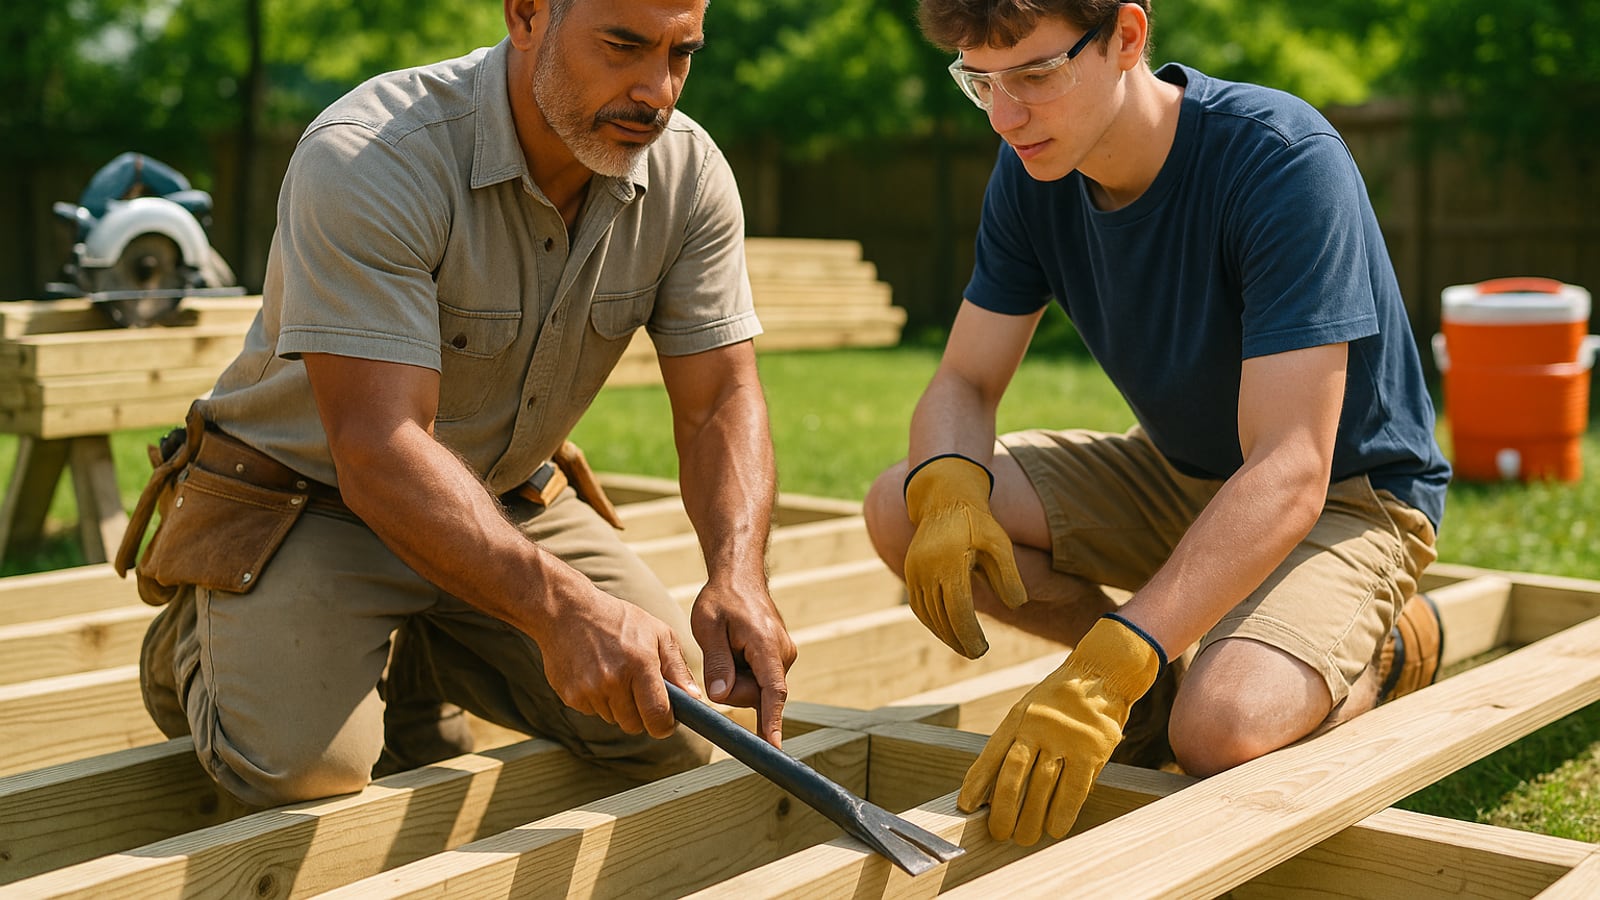
It's a Thursday in June and you're three days behind on a 400-square-foot deck. Your buddy's nephew needs summer money. You hand him a pry bar, tell him to be there at seven, and plan to pay him $20 an hour in cash every Friday. Maybe a 1099 in January if you remember.
Two weeks in, he slips off a joist and breaks his wrist.
Your general liability policy almost certainly won't cover him, because GL covers damage to other people and their property, not injuries to people working for you. Workers' comp would have. You don't have workers' comp. And the "contractor" label you gave him in your head is about to get tested by a state agency, an ER billing department and possibly a lawyer. None of them will be impressed.
Most first hires in the trades go wrong exactly this way. Not out of greed. Out of hurry.
The label on the check doesn't decide anything
The IRS looks at the actual relationship, and it sorts the evidence into three buckets.
Behavioral control. Do you decide when he shows up, what order the work happens in, and how he does it? Do you train him? That points to employee.
Financial control. Does he bring his own truck and tools, carry his own expenses, have a real shot at making or losing money on a job? Does he work for other people too? That points to contractor.
The relationship. Is it ongoing with no end date? Is the work he does the core of your business? Employee again.
A kid you're teaching to set posts, who rides in your truck, uses your nail gun and works only for you, hits nearly every employee marker there's. Having him sign a contractor agreement doesn't move the needle much. It mostly proves you knew the question existed.
Some states are stricter still. California, Massachusetts and New Jersey use versions of what's called the ABC test, which starts from the assumption that a worker is an employee unless you can prove otherwise. If you're genuinely unsure, the IRS will make the call for you if you file Form SS-8, though it takes a while. Faster route: ask your CPA before you hire, not after.
When a contractor really is a contractor
Subs are real, and plenty of good ones exist. The drywall finisher you bring in for two days who has his own LLC, his own insurance, his own rig and a waiting list of other GCs is a contractor. Pay him on a 1099-NEC if you cross the IRS reporting threshold, which Congress changed recently, so confirm the current number with your accountant.
Before you pay any sub, get:
- A signed W-9, collected before the first check, not in a January scramble
- A certificate of insurance showing his general liability, with you named as certificate holder
- Proof of his own workers' comp if he has employees
- A written scope and price for the job, so he's bidding work, not clocking hours
That insurance paperwork matters more than people think. At your workers' comp audit, uninsured subs can get counted as your payroll, and you'll pay premium on them after the fact. That's a nasty letter to open in March.
What an employee actually costs
Everyone knows the hourly rate. The part that catches people is everything stacked on top of it. So run it.
Example only. Your state, trade and rates will differ. One helper, $20 an hour, 30 hours a week, 50 weeks:
- Wages: $30,000
- Employer share of Social Security and Medicare (7.65%): $2,295
- Federal unemployment (FUTA), which typically works out to $42 a year per employee once the state credit applies
- State unemployment: varies widely by state and your assigned rate
- Workers' comp: rates swing hugely by trade class code. At an illustrative $6 per $100 of payroll, that's $1,800. A roofer could pay several times that. A finish carpenter may pay less.
- A payroll service to handle withholding, deposits and filings: a monthly fee plus a per-employee charge
Call it roughly $34,000 or more to put $30,000 in his pocket, before any bonus or benefits. You'll also owe the paperwork: a W-4 and I-9 on day one, a new-hire report to your state, payroll tax deposits and quarterly Form 941 filings.
Is it worth it? Only if he frees you to bill more hours or finish jobs faster than you could alone. If you've never worked out what your own hour costs, start with this breakdown before you add someone else's. And payroll tax deposits run on their own schedule, separate from the estimated payments you make on your own income, so get your quarterly system straight first. Adding a second set of deadlines to a messy first set is how guys end up owing penalties on both.
The honest concession: for a two-week rush with no ongoing work behind it, a properly insured sub beats a hire every time. Don't create a job you can't keep feeding.
An apprentice is an employee with a plan
"Apprentice" isn't a third tax category. An apprentice is an employee. You pay him on a W-2, you withhold, you carry comp. What makes him an apprentice is the structure around the job: logged hours, a skill progression and usually some classroom time.
That structure pays off if you're in a licensed trade. Electrical and plumbing licenses in many states require documented hours under a licensed pro, and a Registered Apprenticeship through the Department of Labor (apprenticeship.gov is the starting point) gives those hours real weight. Some states offer tax credits or wage help for registered apprentices. Programs vary, so check with your state's apprenticeship office rather than assuming.
The trade-off is real. Registration means paperwork, wage-progression rules and a commitment to actually teach. If you're the kind of guy who'd rather do it himself than explain it, you'll hate it. But if you want a second licensed tradesman in five years who learned it your way, nothing beats it.
And the old code applies here. Send him home a better tradesman every week than he was the week before. That's the real pay.
If your first hire eats at your table
Here's one the brief-reading crowd misses: hiring your own kids. If you run a sole proprietorship, or a partnership where the only partners are the child's parents, wages you pay your child under 18 aren't subject to Social Security and Medicare tax, and wages to a child under 21 aren't subject to FUTA. That exemption disappears if you're set up as a corporation.
The work has to be real, the pay has to be reasonable for the job, and child labor laws still apply. No 14-year-old on a roof. But a teenager sweeping job sites, loading the trailer and learning how a business actually runs, with a real paycheck and a real boss who happens to be Dad? That's one of the best things you can give a kid. Ask your CPA how to document it properly.
Before you post the ad
Make sure the work will be there in month four, not just this week. If the calendar's thin, fill it before you hire. Call the people who already paid you and see what's hiding in your old invoices.
Then set the terms on day one, in writing: start time, phone rules, a 60- or 90-day trial, what gets him a raise and what gets him sent home. Be the boss who pays on Friday before anyone has to ask, who hands over a truck with a full tank, and who doesn't bend on the seven o'clock start.
He'll forget the paperwork you filed. He'll remember what kind of man he worked for.
Marcus Vale
Editor-in-Chief
Twenty years in magazines, most of it deciding what to cut. Writes about work, discipline and the decisions that compound.
Watch
Worth an hour of your evening
More from Self-Employed Men.
From channels we rate. Plays on YouTube.
Read next