Your Rehab Number Is Wrong. Fix It Before You Buy.
How to walk a fixer-upper, build a real scope of work, and price it close enough that the surprises don't own you.
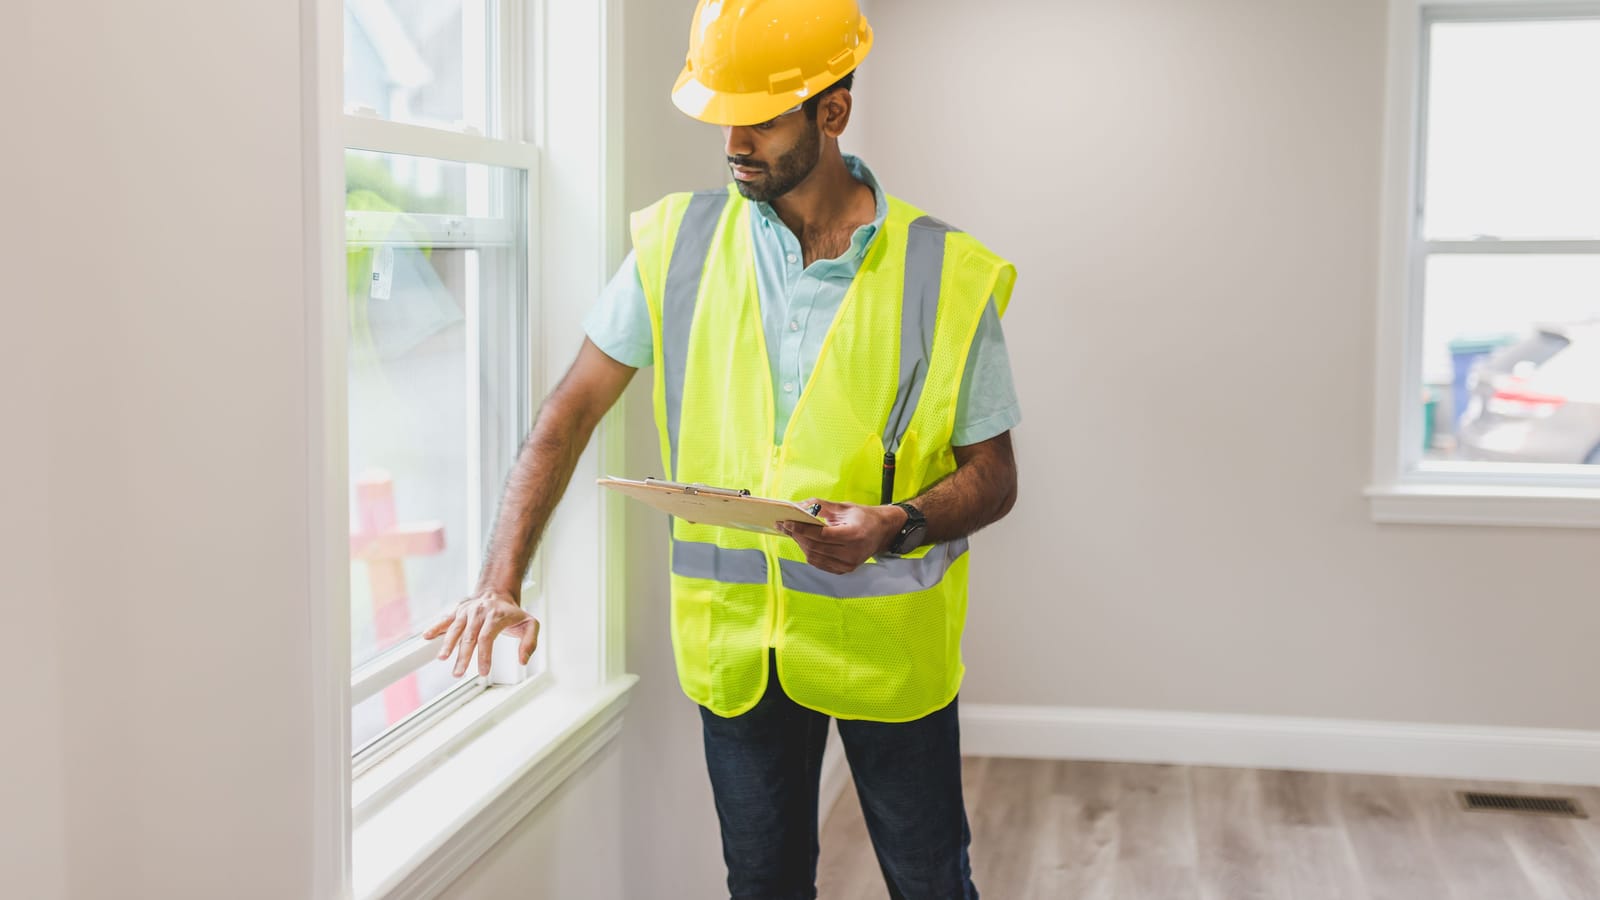
The number you scribble on your phone while standing in a stranger's kitchen is almost always low. Not a little low. Low by a third, sometimes by half, because you priced what you could see and the house charges you for what you couldn't.
So stop estimating with your eyes. Estimate with a scope sheet, three bids, and a contingency you're not allowed to spend on granite.
What follows is general education. Contracts, disclosures, permit rules, licensing and tax treatment vary enormously by state and county, and every dollar figure below is an illustrative example, not market data. Before you sign anything, talk to a licensed real estate attorney, a CPA, your lender and an agent who works your zip code.
Walk the house in the order that money flows
Amateurs walk in and look at the kitchen. The kitchen is the last thing that matters.
Go in this order, and write down what you see even when you can't price it yet:
- Water. Roof age, flashing, gutters, grading away from the foundation, stains on ceilings, musty smell in the basement, the crawlspace.
- Structure. Cracked or bowed foundation walls, sloping floors, doors that won't latch, a sagging ridgeline, sistered joists somebody added in a hurry.
- Sewer and supply. Cast iron or clay lateral, galvanized supply lines, a well or septic instead of city service.
- Electrical. Panel brand and amperage, knob and tube, aluminum branch wiring, two-prong outlets everywhere.
- HVAC. Age sticker on the furnace and condenser, ductwork, whether there's any return air at all.
- Envelope. Windows, siding, insulation in the attic.
Only then do you look at cabinets and paint. Cosmetics are the part you can control. The first six are the part that controls you.
The scope of work is the whole job
A rehab budget isn't a number. It's a document. Build a line-item scope of work: room by room and system by system, each line with a quantity and a unit.
"Bathroom" isn't a line. "Remove and replace 40 sq ft of floor tile, new 30-inch vanity, new toilet, new tub surround, relocate nothing" is a line. The difference between those two sentences is about four thousand dollars and a month of arguing.
Write it before you get bids. If you hand three contractors three different verbal descriptions, you'll get three bids you can't compare, and you'll pick the low one, and the low one will find things.
Get real bids inside your due diligence window
The inspection period isn't just for deciding whether to buy. It's for pricing.
Ask the seller's agent for access for your trades. Most will allow it. Bring a general contractor if you're using one, and bring the specialists for anything with a five-figure tail: a licensed electrician if the panel is questionable, a plumber, an HVAC contractor, a sewer scope company with a camera, and a structural engineer if anything about the foundation makes your stomach tighten.
A sewer scope runs a couple hundred dollars in a lot of markets. A collapsed lateral under the front yard can run five figures once the city gets involved with the street cut. That's the best ratio in this business.
A real bid has a written scope, a materials allowance, a start window, a payment schedule, the contractor's license number, and proof of insurance. A text message that says "12k for the kitchen" isn't a bid. It's an opening position.
Price per square foot lies to you
You'll hear people throw around a dollars-per-square-foot rehab number. It's fine for a gut check on a 3,000-square-foot house that needs everything. It's useless on a 1,200-square-foot ranch that needs a roof, a panel and nothing else, and it's dangerously optimistic on any house where the work is concentrated in kitchens and baths.
Bathrooms and kitchens carry the cost per square foot. Bedrooms are paint and flooring. A house with one bath and one kitchen costs far less to turn than the same square footage with three baths, and the spreadsheet with a single blended number can't tell them apart.
An illustrative worked example
Made-up house, made-up county, made-up prices. Use it as a shape, not as a quote. A 1,400-square-foot ranch built in 1962, one bath, dated but dry:
- Roof, tear-off and replace: $13,000
- 200-amp panel and service upgrade: $3,200
- Furnace and AC replacement: $9,500
- Kitchen, stock cabinets and laminate counters: $16,000
- Bathroom, full gut: $9,000
- Flooring throughout: $7,500
- Interior paint: $4,500
- Windows, eight units: $6,400
- Exterior paint, gutters, landscaping: $5,000
Subtotal: $74,100.
Now the parts nobody puts on the whiteboard. Permits and plan review, call it $1,800. Dumpsters, three pulls, $1,500. Utilities running during the work, $600. Holding costs while you own a house nobody lives in, four months of payment, taxes and insurance at $1,650 a month, $6,600. Contingency at 15 percent of the construction subtotal, $11,100.
All in: roughly $95,700 against the $74,100 you would have said out loud in the driveway. That gap is the entire reason people lose money on fixer-uppers.
Contingency isn't a slush fund
Fifteen percent is a reasonable floor on a cosmetic rehab where the systems check out. Twenty to twenty-five is closer to honest on anything pre-1970 where you're opening walls.
And it's for discovered conditions, not for upgrading to the nicer tile. Write that rule down and hold yourself to it, because the day the drywall comes off and there's no header over the kitchen opening, you'll want that money to exist.
The old-house surprises that actually bite
Pre-1978 paint brings the EPA's Renovation, Repair and Painting rule into play, which means certified firms and containment practices on disturbed painted surfaces. Vinyl floor tile and pipe wrap from certain eras can contain asbestos, and abatement is a licensed trade with its own pricing. Knob-and-tube wiring can make an insurance carrier nervous before it makes an inspector nervous. Federal Pacific and Zinsco panels have reputations that will follow you to the appraisal.
None of these are automatic deal killers. All of them are line items you want priced before closing instead of discovered after.
Paperwork that keeps a rehab from going sideways
Get a certificate of insurance naming you, not a photo of a card. Get a W-9. Use a written contract with a payment schedule tied to completed milestones, and resist the deposit that's half the job up front. Every change goes on a written change order with a price, signed before the work happens. Collect lien waivers with each payment, conditional on progress and unconditional at the end, including from subs and suppliers where your state's mechanic's lien law allows them to file against your property even though you paid the general.
Pull permits. Yes, it's slower. An unpermitted addition is a discount you'll hand to your buyer's agent someday, with interest.
The one habit that separates the two kinds of buyers
Price the house twice. Once in the driveway, fast, to decide whether it's worth an offer. Then again on paper, line by line, with three bids and a contingency, to decide whether you'll actually close.
If the second number kills the deal, the deal was always dead. You just found out while it was still free.
Ray Okonkwo
Money & Business
Former commercial banker turned small-business owner. Covers salary, credit, margins and the arithmetic nobody does before signing.
Watch
Watch how it's done
Picked for this article.
From channels we rate. Plays on YouTube.
BiggerPockets
3 Ways to Estimate Rehab Costs (Even on Your FIRST Deal)
Real Estate Rookie
How to Estimate Rehab Costs (Flipping Houses and BRRRRs)
Read next