Quick answer: The day a payment lands, move about 30 percent of it into a separate savings account you don't touch. Pay the IRS from that account four times a year. Do those two things and most of the rest is paperwork.
This is general education, not tax advice. Your situation is yours. A CPA or enrolled agent can tell you your real numbers.
A good year that ends in a bad March
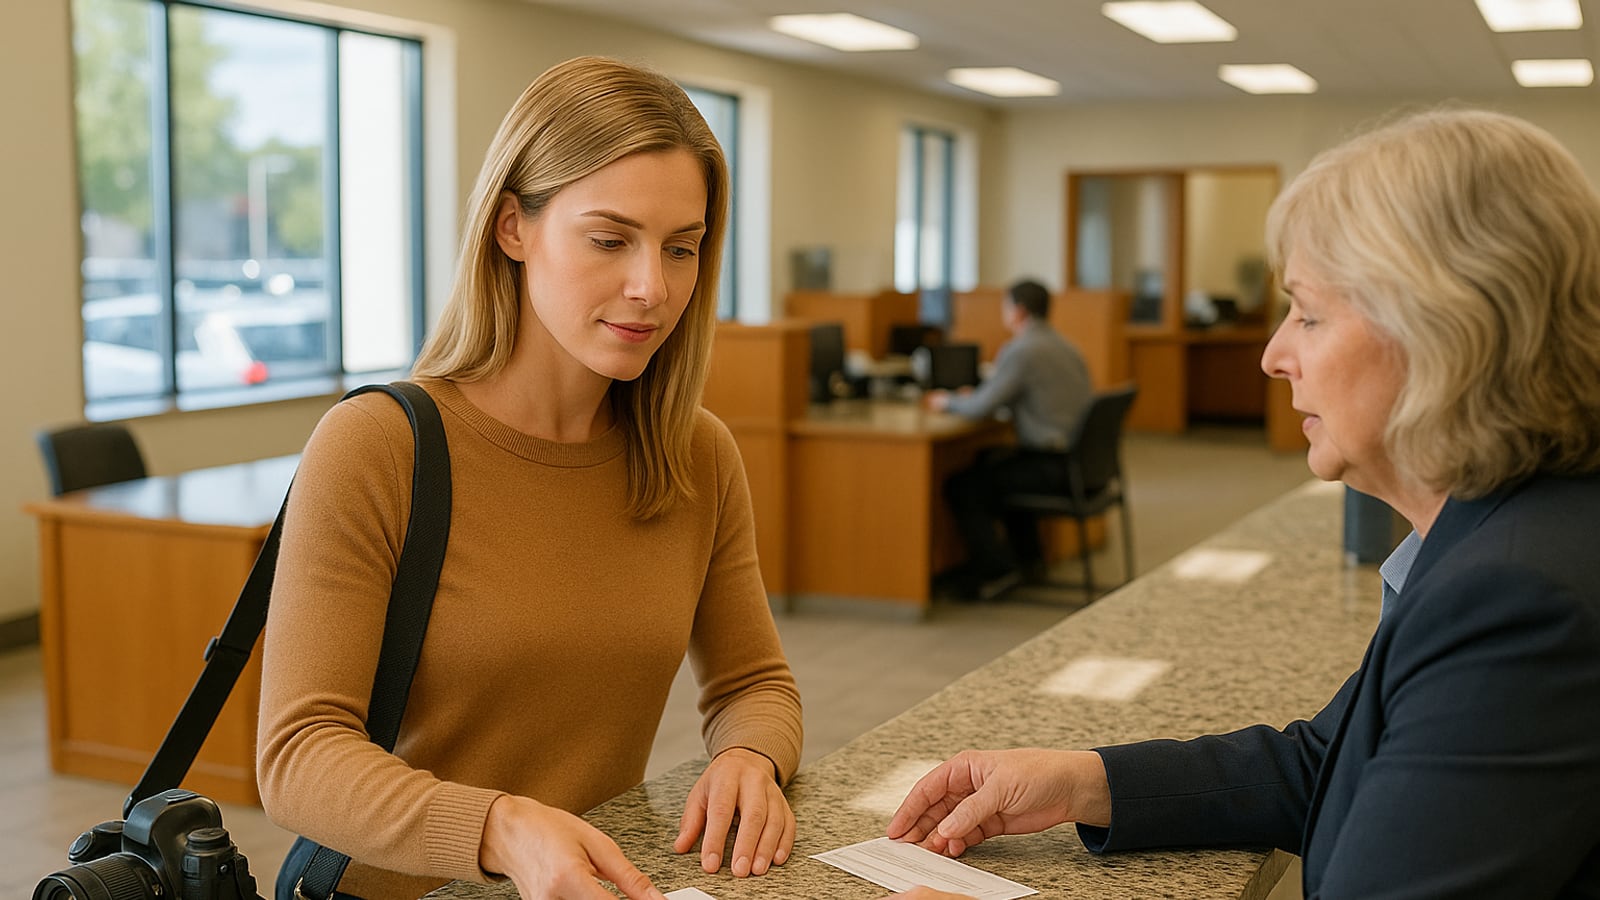
An example, not a real client. A woman runs a wedding photography business out of her house. It's her first full year since the side hustle started costing her more than the job. She books steadily and clears $48,000 after expenses. The money goes where money goes: mortgage, the kids' braces, a new lens she genuinely needed.
In March her preparer runs the numbers. She owes roughly $6,800 in self-employment tax before a single dollar of income tax gets added. There's also a penalty for not paying during the year.
Her business did fine. Her bookkeeping didn't.
Why the bill is bigger than you expect
When you had a job, your employer paid half your Social Security and Medicare and quietly took the other half out of every paycheck. You never saw either one.
Now you're the employee and the employer. Self-employment tax is 15.3 percent: 12.4 percent for Social Security (up to that year's wage cap) and 2.9 percent for Medicare. It's figured on 92.35 percent of your net profit, and it kicks in once your net earnings from self-employment hit $400 for the year. In the example, $48,000 times 0.9235 times 0.153 is about $6,782.
Then comes federal income tax, and state income tax in most states. You do get to deduct half of your self-employment tax when you figure income tax, so it isn't a full double hit. It still stings.
And nobody withholds any of it. That's the whole problem. It's also one more reason your rate isn't your old salary divided by forty hours. Your price has to carry a tax bill your old paycheck handled invisibly.
Three accounts, starting this week
Open these and never mix them:
- Business checking. Every client payment goes in. Every business expense comes out. Nothing personal, not even once, not even the "I'll pay it back" grocery run.
- Tax savings. A separate savings account, ideally at a different bank so it's a little annoying to reach. Your 30 percent goes here the same day money comes in.
- Your pay. Transfer yourself a set amount on a schedule, like a paycheck. The family budget runs on this, not on whatever's sitting in business checking.
The balance in your business account is a story you tell yourself every morning. Separating the money makes it tell the truth.
It also makes bookkeeping about ten times easier. When every line in an account is business, you're not squinting at a Target charge in November trying to remember if it was printer ink or a birthday present.
About that 30 percent
It's a common starting point, not a law. If you live in a high-tax state or you're earning well, you may need more. If your expenses are heavy, 30 percent of every gross payment will overshoot.
Overshoot anyway in year one. A surplus in April is a pleasant problem. After your first return, your preparer can look at what you actually owed and give you a sharper percentage.
Paying four times a year
The IRS expects self-employed people to pay estimated tax as they go. The usual due dates are April 15, June 15, September 15 and January 15 of the following year. When a date lands on a weekend or holiday, it moves to the next business day. You can pay through IRS Direct Pay or your IRS online account in about five minutes. Put all four dates in your phone now, with a reminder a week early.
Two ways to make this easier:
The safe harbor. You generally avoid the underpayment penalty if your on-time payments during the year add up to at least 100 percent of last year's total tax, or 110 percent if last year's adjusted gross income was over $150,000. Once you have a prior year to work from, divide that number by four and pay it. You may still owe more in April, but you won't be penalized for it.
Your husband's paycheck. If you file jointly and he has a W-2 job, he can update his W-4 to withhold extra from each check to cover your business tax. Withholding counts as paid evenly across the year, even if he bumps it up in the fall. For a lot of couples that beats four separate payments. Sit down together with a tax pro before you do it. It's also a good excuse for a real money conversation at the kitchen table.
Bookkeeping in twenty minutes a week
You don't need an hour of silence. You won't get one, and your kids won't respect office hours anyway. Pick a fixed twenty minutes, say Friday after lunch, and run this list:
- Categorize every transaction in business checking.
- Snap photos of any paper receipts and toss them in one folder.
- Log business miles: date, where, why, how far.
- Send any invoices you've been putting off.
- Check who hasn't paid you, and follow up.
- Move the 30 percent if you forgot to.
For tools, a spreadsheet is fine in year one. Wave has free accounting software. QuickBooks Online costs money but your preparer probably already knows it. The best tool is the one you'll actually open on a Friday.
Keep records for at least three years after you file. Some situations call for longer, so ask your preparer.
Deductions, the honest version
Legitimate costs of doing business lower your profit, and with it both taxes. The common ones: supplies, software, a business share of your phone and internet, professional fees, business miles (using the IRS standard rate for that year, or actual costs), and retirement contributions to something like a SEP IRA or solo 401(k).
A few with strings attached:
The home office. It has to be used regularly and exclusively for business. The dining table where you edit photos and your son does fractions doesn't count. A spare bedroom that's only an office does. The simplified method is $5 per square foot, up to 300 square feet, so $1,500 at most.
Health insurance. Self-employed people can often deduct premiums. Generally not for any month you were eligible for a plan subsidized by an employer, and that includes your husband's employer. Ask before you claim it.
The family trip. A vacation with one client coffee in the middle is a vacation. Don't.
And a word on cash. Sooner or later a client will offer to pay "off the books to keep it simple." Say no, nicely and firmly. Cash is income, and a business built on hiding some of its money is one bad year away from real trouble. Your kids are watching how you handle this stuff even when you think they aren't.
When to bring in a pro
Get help for your first return as a self-employed woman. Full stop. An enrolled agent or CPA will catch things you'd miss, set your savings percentage, and flag state rules that vary more than you'd guess.
Leave their desk better than you found it. Hand over clean, categorized books instead of a shoebox. You'll pay for fewer hours, and you'll become the client they're glad to hear from. Then pay their invoice the week it arrives. You know exactly how it feels when people don't.
For Canadian readers: the principles carry over, but the rules don't. You pay both halves of CPP on self-employment income. You generally must register for GST/HST once your revenue passes $30,000 over four consecutive calendar quarters, and the CRA may ask for tax instalments. Talk to a Canadian accountant.
The real goal
Nobody frames her tax return. But the woman who writes a big check in April without her stomach dropping has something better than a big year.
She has a business that can survive a bad one.
Ray Okonkwo
Money & Business
Former commercial banker turned small-business owner. Covers salary, credit, margins and the arithmetic nobody does before signing.
Watch
Worth an hour of your evening
More from Self-Employed Women.
From channels we rate. Plays on YouTube.
Read next