How to Make a Will Your Spouse and Executor Can Carry Out
A will only works if it's signed correctly, matches your account forms, and can be found. Eight steps to get there, and the one error that undoes most of them.
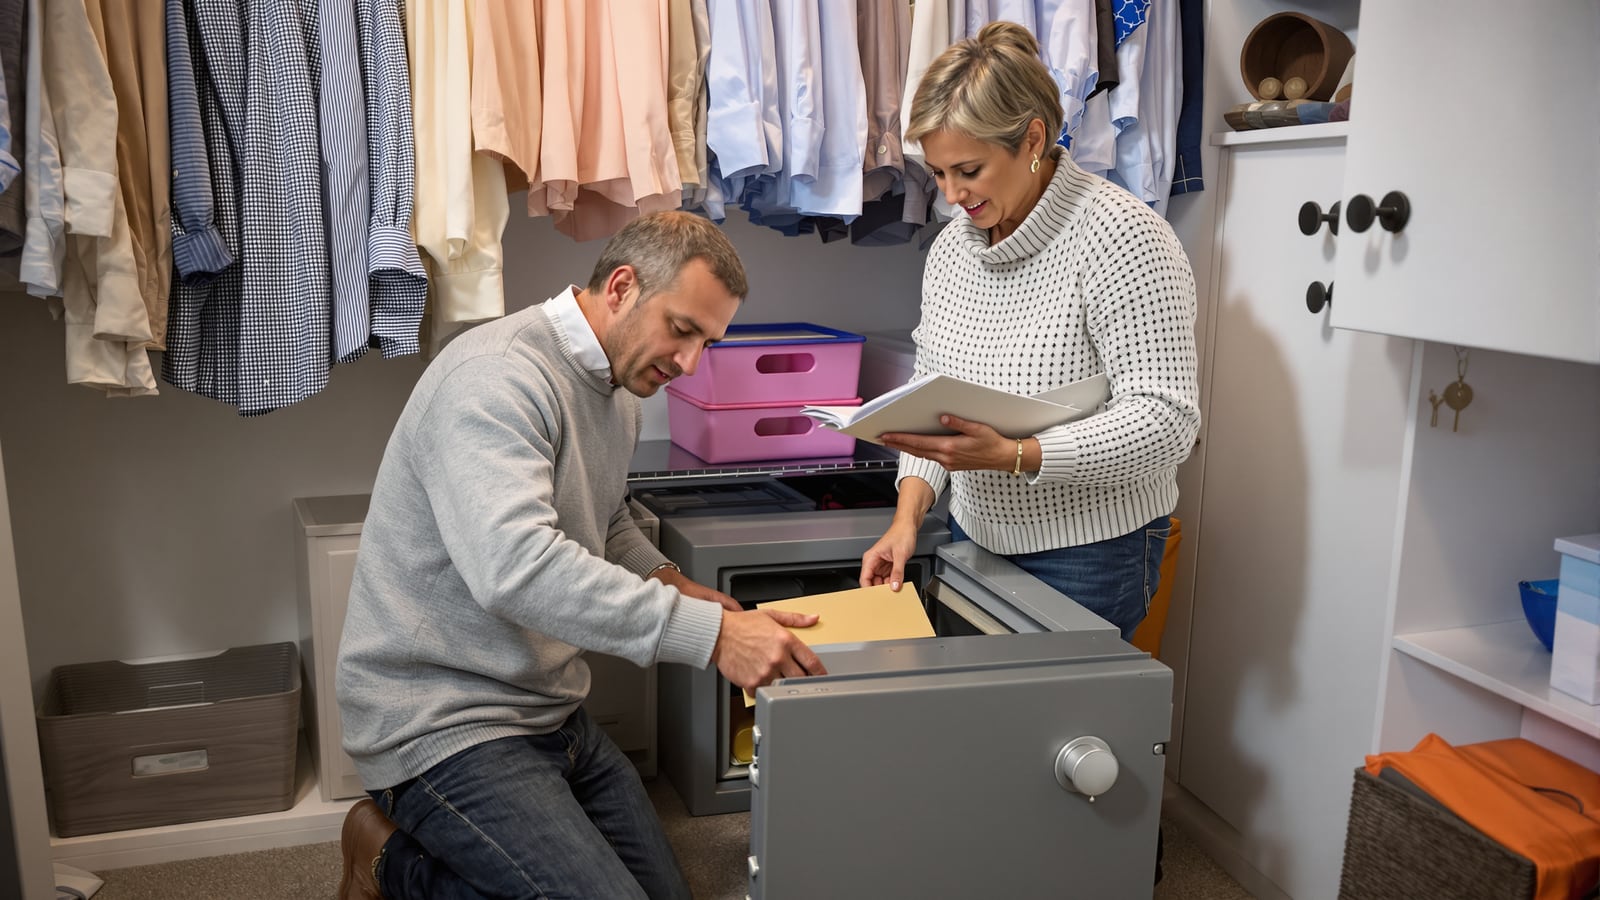
A will your spouse and executor can carry out is a signed, properly witnessed document that names an executor and a backup, agrees with the beneficiary forms on your accounts, sits in a place where someone can find the original, and comes with a one-page list of what you own and where. Miss any one of those and the paper you paid for turns into a problem for the person you meant to help.
Here are the steps, in order.
1. Pick an executor and a backup, and ask them first
Your spouse is the usual choice. Name a second person in case your spouse can't serve, or in case you're both gone. Pick for competence, not for birth order. The executor files court papers, pays bills, and answers to your family for a year or more. The oldest son who loses every piece of mail isn't the man.
Call the person and ask. Some states call this role "personal representative," but it's the same job. Tell them where the paperwork will be.
2. Inventory what the will actually controls
This is the step people skip, and it's where wills fail. Your will controls only what's in your name alone, with no named beneficiary and no co-owner. It doesn't control:
- 401(k)s, IRAs, and pensions, which go to whoever's named on the form
- Life insurance, same rule
- Bank accounts marked payable-on-death, and jointly owned accounts
- A house titled jointly with right of survivorship
Pull the beneficiary form for every one of those. Write down who's named. That list is your real estate plan, and the will fills in the gaps around it.
3. Decide who gets what, in plain words
Keep it simple. Spouse first is the norm for married couples, then children. Name specific people with full legal names. "My truck to my son Daniel Reyes" is clear. "My truck to my son" is a fight if you have two.
If you have minor children, do two things. Name a guardian, and name a backup. And don't leave money straight to a child under 18, because a court will manage it until they come of age. Set up a trust in the will, or name a custodian under your state's Uniform Transfers to Minors Act, and pick the age when they get control. Twenty-five is common. Eighteen is early for most boys, and for most girls too.
Know your state's rules on a surviving spouse. In most states a spouse has a legal right to a share of your estate no matter what the will says, called the elective share. Nine states are community property states: Arizona, California, Idaho, Louisiana, Nevada, New Mexico, Texas, Washington, and Wisconsin. There, property earned during the marriage is generally treated as owned half by each spouse. Florida limits who can inherit your homestead if you have a spouse or minor children. You can't plan around these rules by guessing.
4. Draft it the right way for your situation
You have three honest options.
An attorney. Worth it if you own a house, have minor children, run a business, or have a blended family. Ask for a flat fee for a simple will. Many estate lawyers quote a few hundred dollars up to around a thousand, and prices vary by city. Get the number before you book.
A reputable online service. Fine for a plain married couple with modest assets and no surprises. Our guide on writing a will without paying a fortune covers the cheaper routes.
Handwritten. About half the states honor a will written entirely in your own hand, called a holographic will. The rest don't. Even where it's legal, it's the easiest kind to challenge. Don't use it unless it's all you've got.
5. Sign it exactly the way your state requires
This is where good intentions die. Most states require your signature and two adult witnesses who watch you sign. Pick witnesses who aren't getting anything under the will. A beneficiary as witness can void their gift or invite a challenge in many states.
Then add a self-proving affidavit, signed by you and the witnesses in front of a notary. Most states accept one. It lets the court accept the will without tracking down the witnesses years later. Notary fees are set by state and are usually small. Your bank may do it for free if you're a customer.
Louisiana runs on its own rules, with a notary and two witnesses for the standard form. Several states now permit electronic wills or remote witnessing, and others don't. Check your state bar's website or your state court's probate page before you sign anything online.
6. Store the original and tell people where it is
Courts generally want the original, not a copy. Put it in a fireproof home safe, or leave it with your attorney. Tell your spouse and your executor where it is and how to open it.
A bank safe deposit box works only if your spouse can get in. In some states, a box held in your name alone gets sealed at death until a court orders it opened. If you use a box, add your spouse as an owner.
7. Write the letter your executor will thank you for
This isn't a legal document. It's a few pages in a folder. List:
- Every bank, brokerage, and retirement account, with the institution's name and the last four digits
- Insurance policies and the agent's phone number
- Your attorney, accountant, and employer's benefits contact
- The mortgage, loans, and monthly bills
- Where the vehicle titles, deed, and tax returns are
- Where your Social Security card and birth certificate are. If either is missing, here's how to replace them.
Don't put passwords in the will itself. A will filed with the court usually becomes public record. Keep passwords in a separate, secured place your spouse knows about.
Your executor will also need certified copies of the death certificate, usually ordered in batches of ten or more from the funeral home. They'll also file IRS Form 56 to notify the IRS they're acting for the estate, and request an EIN for the estate on Form SS-4. The estate files Form 1041 if it earns $600 or more in income. They'll appreciate knowing where to start.
8. Review it every few years and after any big event
Marriage, a birth, a death, a divorce, a move to another state, a new house, a business sale. Any of them can break a will. Read it every three to five years regardless. If you change something small, don't scribble on the original. Sign a formal amendment, called a codicil, with the same witness rules, or just redo the will.
The mistake that undoes everything
Updating the will and forgetting the forms.
A man remarries and rewrites his will to leave everything to his new wife. His old 401(k) still names his first wife as beneficiary. When he dies, the plan pays his first wife. The Supreme Court settled this in Egelhoff v. Egelhoff (2001) for employer plans governed by federal law: the plan documents win, and state law doesn't change that.
The new wife can sue, and she'll likely lose.
Fix it in an afternoon. Log in to every account, read the beneficiary line, and confirm it matches what you've written in the will. Do it again after every life change.
A will isn't something you leave for your family. It's something you do for them while you can still do it right. Leave the folder cleaner than you'd want to find it, and nobody has to ask what you meant.
If your situation involves a business, a blended family, a special-needs child, or an estate large enough to trigger state estate tax (Oregon and Massachusetts, among others, tax at much lower thresholds than the federal government), pay an estate attorney in your state. That's their job, and it's worth it.
Ray Okonkwo
Money & Business
Former commercial banker turned small-business owner. Covers salary, credit, margins and the arithmetic nobody does before signing.
Watch
Worth an hour of your evening
More from How To.
From channels we rate. Plays on YouTube.
Read next