

How to Update Your Beneficiaries on Insurance and Retirement Accounts
One form on file decides who gets the money, and it beats your will. Here's how to check every account in an afternoon and fix what's wrong.
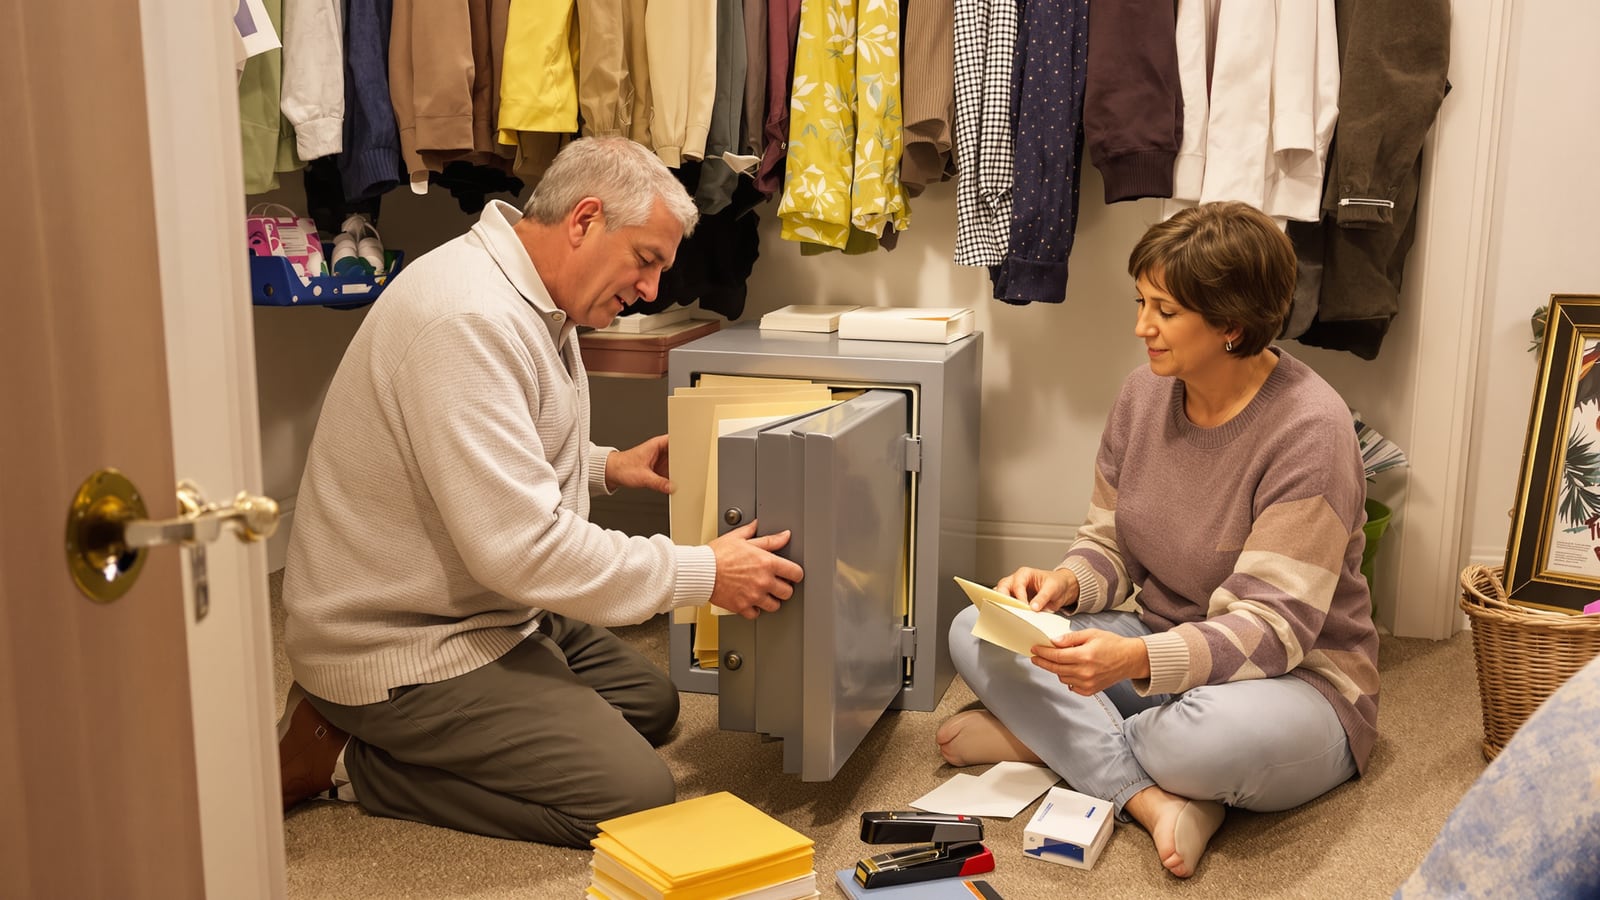
Log in to each account, find the beneficiary page, correct the names and percentages, and keep the confirmation. That's the whole job. Plan on one afternoon and a cup of coffee. It usually costs nothing.
It matters because the beneficiary form on file with your insurer or plan administrator controls who gets that money. Your will doesn't. Your ex-wife's name from 2009 on a dusty life insurance form beats whatever your lawyer drafted last spring. If you haven't looked at these forms since you signed them, assume at least one is wrong.
1. Make a list of everything with a beneficiary line
Most men remember the life insurance and forget the rest. Go through all of these:
- 401(k), 403(b) or other employer retirement plans, including old ones from past jobs
- Traditional and Roth IRAs
- Employer-paid group life insurance (often one or two times your salary, and easy to forget)
- Individual term or whole life policies
- Annuities and pensions
- Health Savings Accounts
- Bank and brokerage accounts with a payable-on-death or transfer-on-death designation
If you've served or worked for the federal government, add these: SGLI or VGLI, the Thrift Savings Plan, FEGLI, and your FERS or CSRS annuity.
Write each one down with the company name, the account number, and who's currently listed. For most accounts you'll only know that last part after you log in.
2. Decide who gets what before you touch a form
Nothing slows this down like standing at the keyboard and realizing you haven't decided. Settle it first.
Name a primary beneficiary and a contingent one. The contingent is who gets the money if the primary has died or can't be found. Percentages for each tier must add up to exactly 100. Ninety-five percent will get your form kicked back, or worse, create a mess later.
Use full legal names, dates of birth, and relationships. "My kids" isn't a beneficiary. Three named children with birthdates is.
If a minor child is a beneficiary, stop. Insurers and plans generally won't hand money straight to a child, so a court may appoint a guardian to manage it, which is slow and public. The usual fixes are naming a trust or setting up a custodial account under your state's Uniform Transfers to Minors Act. The age when the child takes control varies by state, from 18 to 25. This is the one step where an hour with an estate attorney earns its fee. If you don't have a will yet, start with How to Write a Will Without Paying a Fortune, then come back.
3. Get the current form from the source
Don't download a form from a random site. Beneficiary forms are specific to each company, and they update them.
- Employer 401(k) or group life: Use the plan's website or your HR benefits portal. Open enrollment is a natural time to do it, and switching health plans usually walks you past the same screen.
- IRA or brokerage account: Log in to Fidelity, Vanguard, Schwab, or whoever holds it. Look under "Account Features" or "Profile." Most take online changes.
- Individual life insurance: Call the carrier or your agent and ask for the change-of-beneficiary form. Some are online. Some still want paper.
- Federal and military: SGLI changes run through the SGLV 8286 form or the online system on milConnect. TSP uses form TSP-3. FEGLI uses SF 2823. FERS and CSRS annuity uses SF 3102. Each agency's site has the current version.
Whatever you use, the old designation is replaced, not added to. Re-enter everyone you want, not only the new name.
4. Check the spouse rule
This is where people get tripped up, and where rules differ.
Employer plans (401(k), 403(b)). Federal law gives your spouse the automatic right to be the beneficiary. If you want to name someone else, say your kids or your mother, your spouse generally has to sign a written consent, witnessed by a notary or a plan representative. No signature, no change.
IRAs. The federal consent rule doesn't apply. But in community property states (Arizona, California, Idaho, Louisiana, Nevada, New Mexico, Texas, Washington, and Wisconsin), a spouse may have legal claims to part of the account regardless of the form. Alaska allows couples to opt in.
Life insurance and divorce. Some states cancel an ex-spouse's beneficiary status automatically when a divorce is final. Many don't. And for employer plans, the Supreme Court held in Egelhoff v. Egelhoff (2001) that federal law overrides those state statutes, so the form on file wins. Don't count on a statute to clean up after a divorce. Change the form.
If your situation involves a second marriage, children from a first one, or a large estate, talk to an estate attorney. A notary typically costs a few dollars, and many banks do it free for customers. The attorney is the bigger expense, and the cheaper one compared with a family lawsuit.
5. Complete the form and submit it
Print clearly or type it in. Sign where it says sign. If spousal consent is required, get the notary or plan rep before you mail anything. Send paper forms by a method that gives you tracking, or upload through the secure portal.
Don't leave blanks. A form missing a Social Security number or a percentage can be rejected without anyone telling you.
6. Get the confirmation in writing
Online changes usually generate a confirmation page or email. Save it as a PDF. For paper, call two weeks later and ask the company to confirm that the new designation is on file, then ask them to send it in writing.
Keep copies in one folder, paper or digital, and tell your spouse or someone you trust where it is. It does no good if no one can find it.
7. Put a date on the calendar
Check these again after any of the following: a marriage, a divorce, a birth or adoption, a death in the family, or a new job with a new plan. Even with no big event, look once a year. January works. Pick a day and stick to it.
One more reason to stay current: since 2020, most non-spouse heirs who inherit an IRA or 401(k) must empty it within ten years. Whoever you name should know that's coming.
The mistake that costs families the most
Assuming the will, or the divorce decree, handles it.
It doesn't. A will controls property that passes through probate. Retirement accounts and life insurance pass by contract, outside of probate, straight to whoever's on the form. A man can leave a spotless will and a $500,000 policy still goes to his first wife, because nobody changed one page.
The second mistake is the quiet cousin of the first: leaving the contingent line blank. If your primary dies before you do, the money can fall back into your estate, which means probate, delays, and sometimes tax trouble your family didn't need.
You don't have to love paperwork. You just have to do it before somebody else needs it to be done.
Ray Okonkwo
Money & Business
Former commercial banker turned small-business owner. Covers salary, credit, margins and the arithmetic nobody does before signing.
Watch
Watch how it's done
Picked for this article.
From channels we rate. Plays on YouTube.
Mark Robertson, CFP
Should I Update My Beneficiaries? (They Override Your Will)
Fidelity Investments
How To Add And Edit Beneficiaries With Fidelity | FidQs | Fidelity Investments
Read next