Quick answer: Separate business and household accounts. Set a fixed payday built on your worst month. Park the tax money the day it lands. Agree on a dollar figure above which neither of you spends alone.
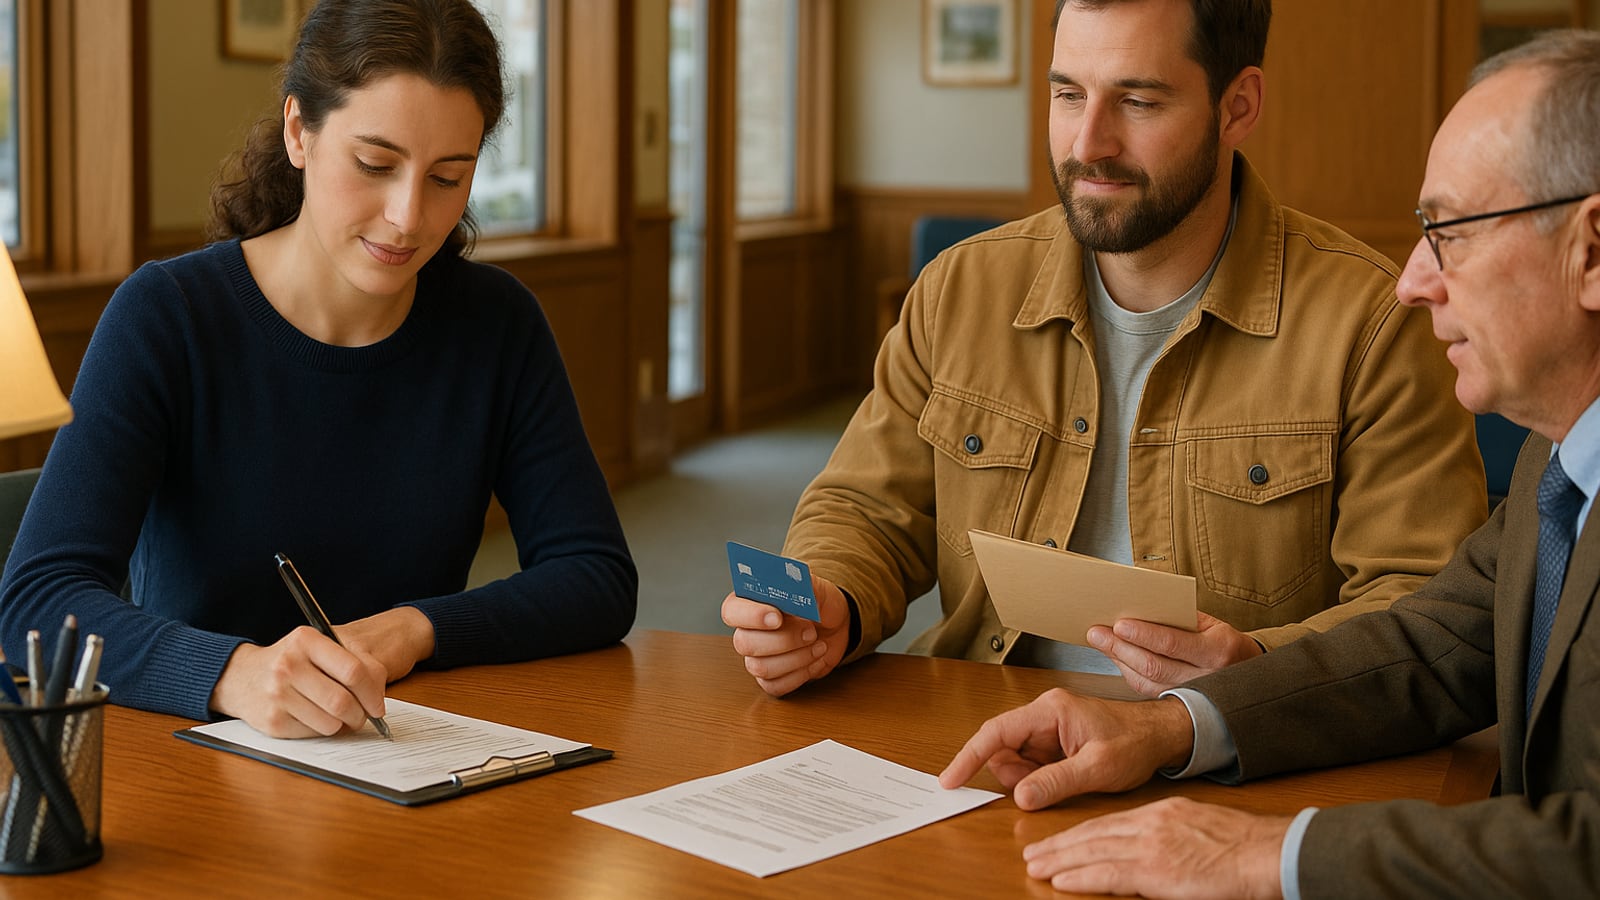
Picture a Tuesday in March. He's at an equipment auction, and a trailer comes up that would save the crew two hours a day. It goes for $11,000, a fair price. He pays with the debit card, because it's the only card, and the only card draws from the only account. On Thursday she goes to pay the mortgage.
Nobody did anything wrong, exactly. The trailer was a smart buy. The mortgage was due. The problem was one pile of money with two jobs and no rules. And the fight that follows won't be about the trailer. It'll be about whether she gets a say.
Most couples start the business out of the household account, because at the beginning there's nothing to separate. That works for about a month. After that, every business decision becomes a household decision and every household purchase becomes a business question.
Rules fix that. Budgets don't.
Two accounts minimum, and money flows one way
Open a business checking account. Keep a separate household account. Stop running either one through the other.
If you've formed an LLC or a corporation, this matters beyond neatness. Mixing personal and business money is one of the things a creditor can point to when arguing that your company and your family are really the same thing, which can put personal assets like the house within reach. Your attorney can tell you how much that applies to your setup. Your CPA will be grateful either way, because untangling a year of mixed transactions in April is slow and expensive.
The direction matters more than the number of accounts. Money moves from the business to the household on purpose. The household doesn't raid the business when the water heater dies. The business doesn't raid the household when a client pays late. Every crossing is deliberate, and every crossing gets written down.
Pay yourselves on the same day, every time
Pick a payday. The 1st and the 15th, or every other Friday. Move a fixed amount from business to household on that day, whether the month felt rich or thin.
No rule calms a marriage down faster. The spouse who's home with the kids, or who doesn't touch the books, knows what's coming and when. Nobody has to ask. Nobody has to read the other one's face after a big invoice clears.
What that transfer is called depends on your structure. In a sole proprietorship or most LLCs, it's an owner's draw. If you've elected S corporation status, the IRS expects owners who work in the business to take a reasonable salary through payroll, with any distributions on top. Have your CPA set it up correctly once. Then let the calendar run it.
Set the number from the lean month, not the average one. If you bring in $30,000 in June and $9,000 in January, your household lives on January. The good months build the cushion. They don't raise the lifestyle.
The tax money was never yours
Self-employed people pay federal taxes quarterly. Estimated payments are due April 15, June 15, September 15 and January 15, shifting when a date lands on a weekend or holiday. Couples who get into real trouble almost always get there the same way. They spent the tax money in October and met the bill in January.
Open a third account. Move a set percentage of every deposit into it the day it arrives. Your CPA will give you the percentage, because it depends on your income, your state and your structure. Then treat that account like it belongs to someone else, because it does. Don't even glance at it when you're deciding whether you can afford the new truck.
If you want a full system, Mike Michalowicz's book Profit First lays out a method for splitting every deposit across several accounts, including one for taxes and one for profit. Some owners find it too rigid. Even they tend to keep the tax account.
The two-signature number
Agree on a dollar figure. Under it, either of you spends for the business without asking. Over it, you both say yes first.
A small operation might start at $500 or $1,000. A bigger one might set it at $5,000. The exact figure matters less than the fact that you picked it together, on a calm day.
Back to the auction. With a $2,500 line, he calls her from the parking lot. Ninety seconds. She probably says buy it. And now it's their trailer.
The rule isn't about trust. It's about both of you owning the risk. It cuts both ways, too. The spouse who runs the books doesn't get to quietly shuffle money around just because they're the one who can see it. For more on which calls belong to one of you and which belong to both, read run the business together, but never decide everything together.
Each of you gets money nobody asks about
Build a small personal allowance into every payday. Same amount for each of you, into separate personal accounts, spent with zero commentary. Fishing lures. A new cookbook. Lunch with an old friend. Nobody reports on it.
It sounds minor. It isn't. When you work together, eat together and share every dollar, the thing you lose is a little room of your own. An allowance gives it back. It also kills the slow resentment of explaining a twenty-dollar lunch to a business partner who happens to be your husband.
When the business borrows from the house
Sometimes it has to. A big client pays 60 days late and payroll is Friday. Fine. But handle it the way you'd handle it with a stranger.
Write down how much, what it's for and when it comes back. Both of you agree before the money moves.
Then follow the old code. Pay it back before anyone has to ask, and pay back a little more. If the business borrowed $4,000, it returns $4,000 plus enough for a dinner out. That's not accounting. That's the business thanking the family that carried it.
If the business borrows from the household twice in a row, sit down and ask why. Twice is a pattern. Three times means the business isn't paying for itself yet, and that's a harder, more honest conversation you need to have.
Keep the house off the table
Lenders often ask owners to personally guarantee business loans, and when you're both owners, they may want both signatures. Push back where you can. If one guarantee will satisfy them, keep the other spouse's name off it. If the business ever goes under, you want one of you standing on dry ground.
Same thinking for home equity. Plenty of solid companies were started on a home equity line, and sometimes it's the only way in. Decide it together, with your eyes open and a plan for what happens if it goes sideways. The house is where your kids sleep. It gets the most protection, not the least.
A real attorney and a real CPA earn their fees here. General rules can't tell you how your state treats marital property or which structure fits your family.
One hour a month, and never at dinner
Pick one hour a month, same day every month. Coffee and a laptop. What came in, what went out, what's sitting in each account, what's coming due. Make any decision above the two-signature line that could wait.
Then close the laptop. For the rest of the month, money talk is for emergencies. Dinner belongs to the kids. Date night belongs to the two of you. If you can't get through a Saturday without discussing receivables, the business has moved into your marriage, and it ought to be paying rent.
Usually one spouse is better with the books. Let that person own them fully, and let the other own sales, the crew or the product. Split it by results rather than tasks, which is the whole idea behind dividing the outcomes, not the chores.
But the bookkeeper's job includes saying no. "We can't do that this month" has to be a sentence either of you can say without it turning personal. The one who holds that line isn't the villain. They're the reason there's still a business in December.
Write these rules down this week, while nobody's upset. Rules made in a calm month hold up in a bad one. Rules made in a bad month are just the fight, typed up.
Ray Okonkwo
Money & Business
Former commercial banker turned small-business owner. Covers salary, credit, margins and the arithmetic nobody does before signing.
Watch
Watch how it's done
Picked for this article.
From channels we rate. Plays on YouTube.
Ciarra Janelle
HOW TO KEEP BUSINESS AND PERSONAL FINANCES SEPARATE | ciarra janelle
Read next