Stop being your customer's bank on materials
A $3,800 lumber bill on your card isn't a business expense. It's a loan to a stranger, and you're not charging interest.
Quick answer: Tie every payment to a stage of the work and keep the money ahead of the job, never behind it. If you've spent more than you've collected, you're lending, and nobody asked you to.
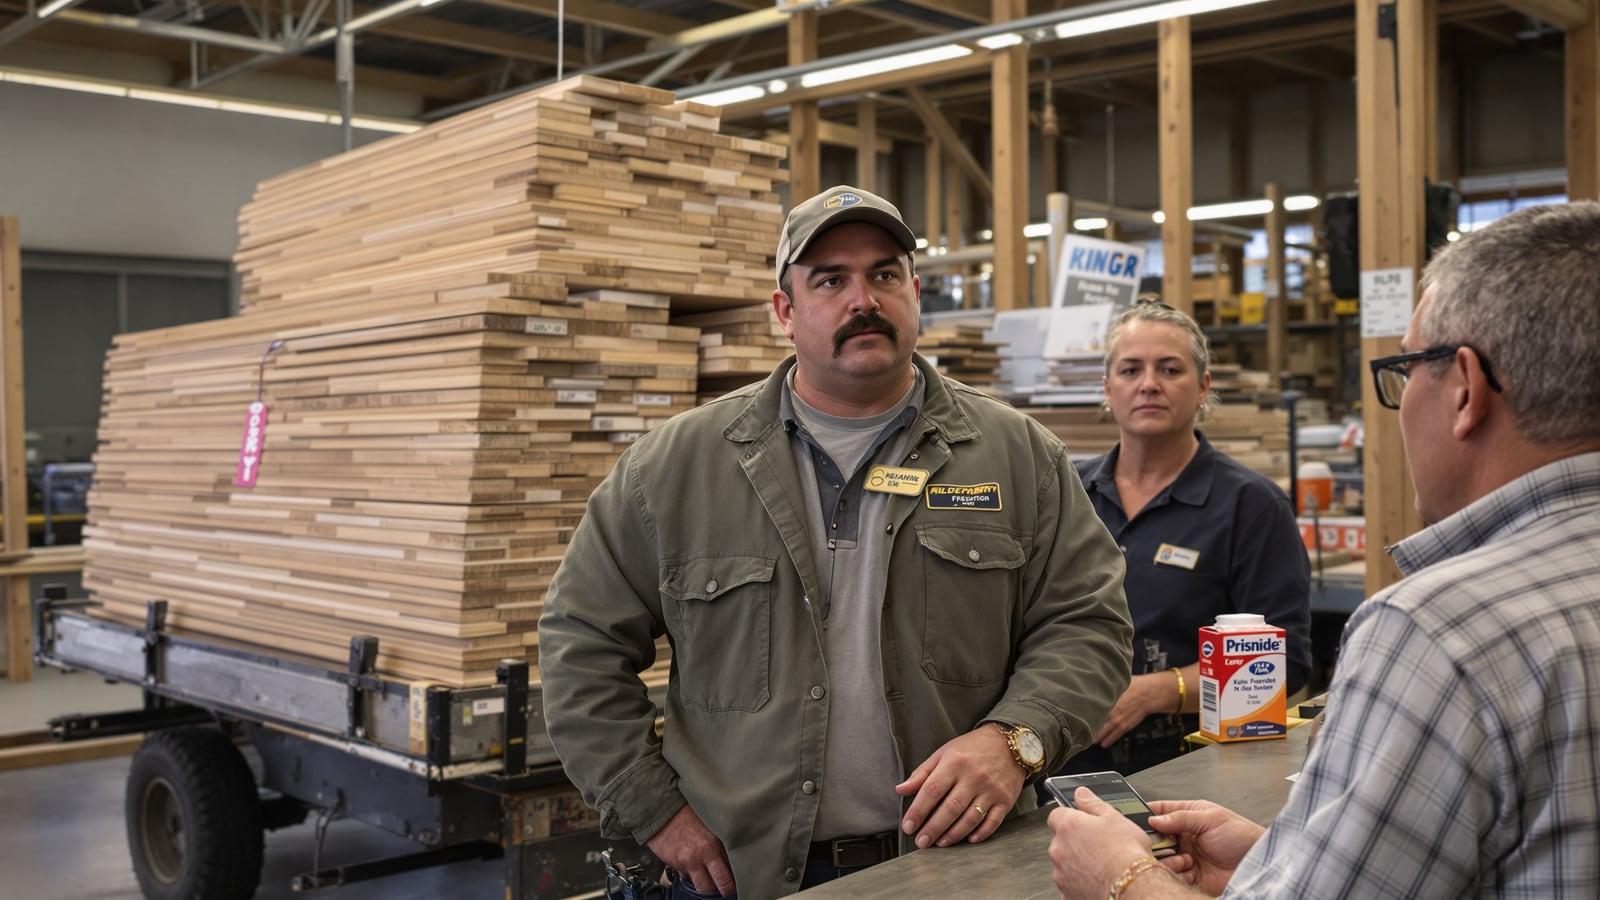
The Tuesday at the lumberyard
You know the scene. The estimate is signed, the homeowner is friendly, and he says, "We'll settle up when it's done." You nod, because you want the job. Then you're standing at the counter putting $3,800 on a card, and the card has a due date that doesn't care how friendly he is.
That's the moment the job went wrong, and the first nail isn't in yet.
Fronting materials feels like part of the trade. It isn't. It's a habit passed down from guys who ran on cash and a handshake, and it works right up until one customer disappears, argues over the finish, or simply pays in 45 days instead of 5. Your suppliers want 30 days at most. Your helper wants Friday. Your customer's schedule isn't on that list.
Call it a draw, not a deposit
Most guys hate asking for a deposit because it sounds like asking for a favor. So stop calling it that.
You're not asking for a deposit. You're running a payment schedule, and every payment is tied to something visible: materials ordered, demo finished, rough-in passed, work complete. The customer is paying for progress, not for your comfort. Said that way, it's hard to argue with, and it protects him too. He never pays for work that isn't there.
Here's a labeled example. It's a made-up number set, not a rule, so adjust it to your trade.
Example: $18,000 bathroom remodel, about $7,000 in materials
- At signing: 30%, or $5,400. This covers the special-order items, like vanity, tile and fixtures, that you can't return.
- When demo is done and materials are on site: 30%, or $5,400.
- When the work is substantially complete: 30%, or $5,400.
- After the punch list is finished: the last 10%, or $1,800.
Run the math at any point in the job and you'll find the money collected is ahead of the money you've spent, including payroll. That's the whole idea.
The cash-ahead test
Before you buy anything for a job, ask one question. If this customer stopped paying today, would I be out of pocket?
Add up what you've spent so far: materials, subs, your helper's hours. Subtract what you've collected. If the number is negative, you're the bank. Fix the schedule, or hold the order until the next draw lands.
It takes about a minute. Do it standing in the truck before you drive to the supplier, not after you've swiped the card.
Where the fronting hides
Not on the big signed contract, usually. It hides in the small stuff.
Change orders. "While you're here, could you also move that outlet?" You say sure. Three days later it's a new fixture, a few hours and a trip to the store, and nobody's written it down. Write it up before you touch it, get a signed text or email, and collect the materials portion first. The sentence "I'll add it to the invoice" has cost tradesmen more money than any bad bid.
Special orders. Windows, custom cabinets, anything with a restocking fee or no returns at all. Those get paid for before you place the order, full stop. If the customer changes his mind after that, it's his decision and his cost, in writing.
Big-ticket items. Appliances, a water heater, a slab of stone. Sometimes the cleanest move is to have the customer buy it himself, or pay the supplier directly. You lose the markup. You also lose the risk, and on a $4,000 item that's usually a fair trade.
What to say when he pushes back
He will, sometimes. Keep it calm and short.
"I work on a payment schedule. Each payment is tied to a stage of the job, so you're never paying for something that isn't finished. It's how I keep the job moving."
If he says "my last guy didn't ask for anything up front," you can answer without an argument: "That's up to him. This is how I work." Then stop talking.
A customer who won't put 30% down on an $18,000 job is telling you something about how the last 10% will go. Listen to it. You're allowed to walk away, and the guys who can walk away are the ones who get paid on time.
The honest trade-offs
This doesn't fit every job.
- On a $300 repair, just invoice when you finish. The paperwork costs more than the risk.
- Repeat customers who've always paid fast can get lighter terms. Earn that with history, not with a good feeling.
- Some states limit how much you can take as a down payment on home improvement work, and the rules differ on licensed work. Check with your state's contractor licensing board, and ask a local attorney to look over your contract before you lean on any of this. Lien rights and notice deadlines are also local and strict.
- You may lose a few jobs to the guy who'll front everything. Let him. He's the one financing your competition's customers.
Put the money where it belongs
When a draw hits, it isn't all yours. Part of it is materials, part is payroll, part is tax. A deposit you've already spent on groceries is how guys end up in April with nothing. Money received generally counts as income when it arrives, and how that works depends on your setup, so ask your CPA. The habit I'd push anyway is moving a slice to a tax account the day the money lands. Quarterly taxes and the one rule that ends the April ambush walks through it.
It also helps to keep customer money in one place, away from your personal spending. One business account and a Friday habit beat any software covers a simple setup. And if your slow months are what make fronting feel unavoidable, Your January was decided back in July is worth ten minutes.
Start with the next estimate
Don't rework every open job tomorrow. Take the next estimate you write and build the schedule into it before you hand it over. Print it on the page. Put the stage next to each number. Say it out loud once, as plain as you'd say the price.
Your customer's bank has a lending department. You don't, and you shouldn't be running one out of your truck.
Ray Okonkwo
Money & Business
Former commercial banker turned small-business owner. Covers salary, credit, margins and the arithmetic nobody does before signing.
Watch
Worth an hour of your evening
More from Self-Employed Men.
From channels we rate. Plays on YouTube.
Read next