Track every dollar for thirty days before you build a budget
Your first budget will be wrong if it's built on guesses. Spend a month writing down what really leaves your account, then build it.
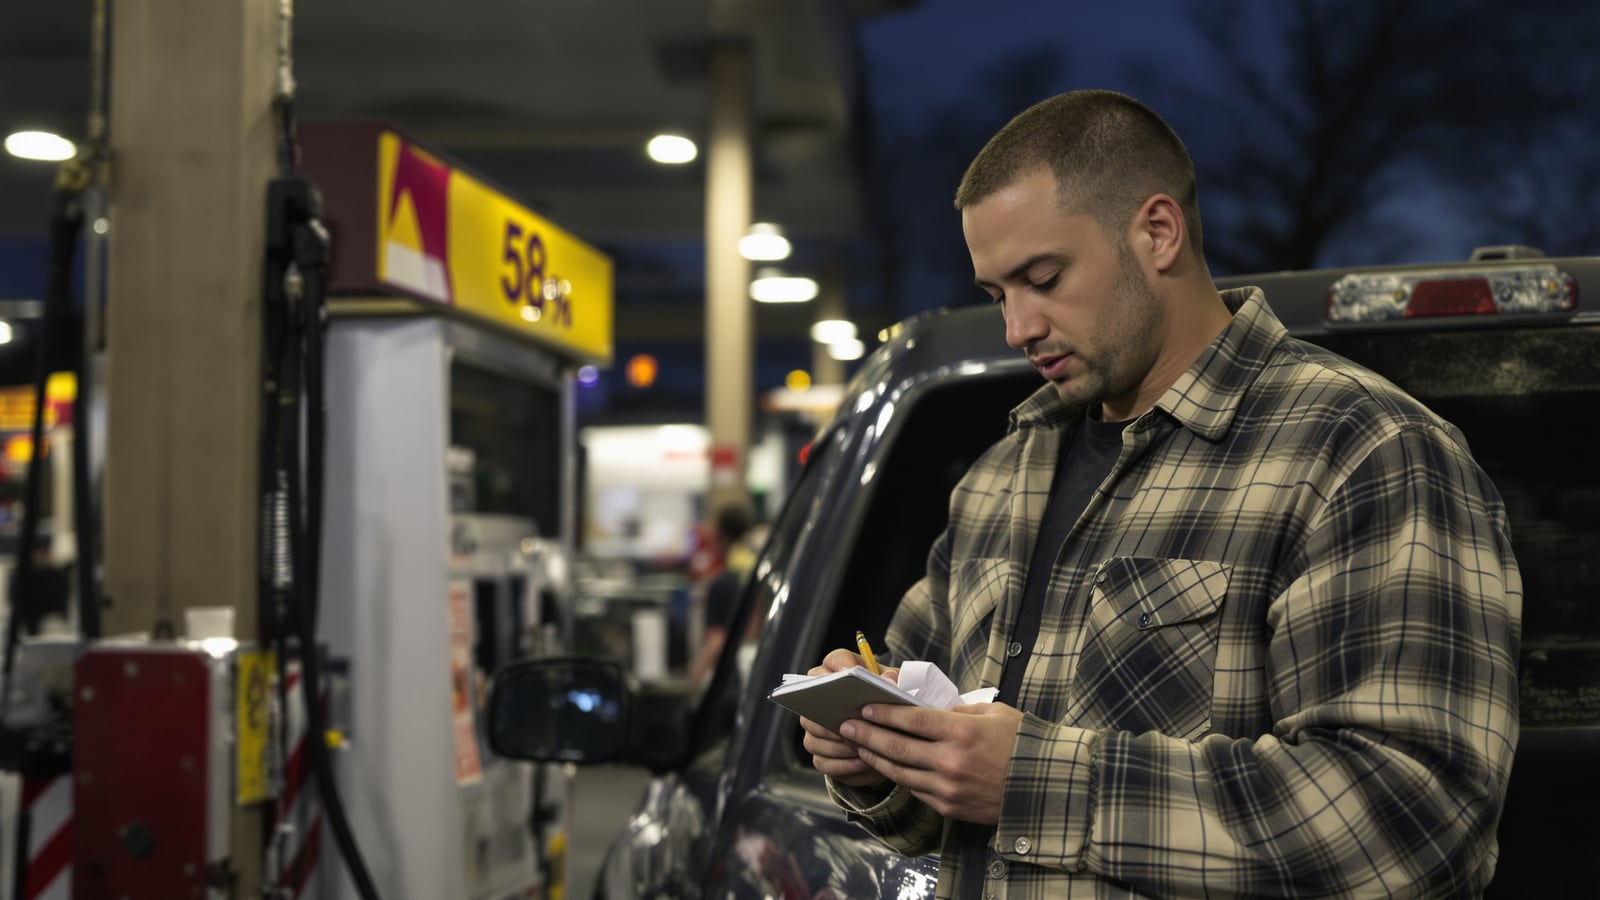
Quick answer: Don't set limits yet. For thirty days, write down every dollar you spend the moment you spend it. On day thirty, build the budget from what you find.
Say you take home $2,400 a month. Rent is $900, phone $55, car insurance $140, and you figure that leaves plenty. Then the month ends and the account sits at $212. Nothing dramatic happened. No one stole anything. It just leaked out in four-dollar and eleven-dollar pieces, and you can't name one of them.
That's normal, and it's fixable. But you can't fix what you can't see.
Why a budget comes second
Most guys start by building a budget: $400 for food, $100 for fun, the rest to savings. Those numbers are guesses. You've never run your own household, so you don't know what groceries cost you, what your truck eats in gas, or how often you'll say yes to dinner out. A budget built on guesses breaks by the second week, and then you decide you're bad with money.
You're not. You were just working without data.
Thirty days of honest records gives you the data. After that, setting limits is arithmetic.
Day zero: write down what's already spoken for
Before you track anything, sit down for twenty minutes and list the fixed bills with their amounts and due dates.
- Rent and utilities, or your share of them
- Phone
- Car payment, insurance and registration
- Student loans or any other debt payment
- Subscriptions, every one of them
Open your bank app and scroll back sixty days to find the subscriptions. You'll find at least one you forgot. Cancel it tonight.
Note the due dates on a calendar. A late fee is the dumbest money you'll ever spend, because it buys you nothing.
The tracking method
Keep it so simple you can't quit it.
Run everything through one account. Use one debit card for all of your spending. Cash is fine, but log it the same minute you hand it over, since cash is where tracking goes to die.
Log it on the spot. Open the notes app on your phone and type the amount and one word. "4.75 coffee." "61 gas." "38 pizza, guys." Takes five seconds. A pocket notebook works just as well, and some men keep it better because the notebook never has a notification to swipe away.
Sort it every Sunday. Spend fifteen minutes with your bank statement and your notes. Check that they match. Then sort each item into five buckets:
- Fixed bills
- Food, split into groceries and eating out
- Car and transportation
- Fun
- Everything else
That last bucket will teach you the most. Haircuts, a birthday gift, a replacement phone charger, the $30 you lent a buddy. These don't recur on a schedule, so they ambush a budget. Name them while they're happening and you'll see the pattern.
What the apps do and don't do
Budgeting apps that link to your bank will sort your transactions automatically. They're handy, and a fine second tool. But they miss cash, they mislabel half of what they catch, and they let you stay passive. In the first month, typing each purchase yourself is the point. It makes you feel what the money costs while it's leaving, which no automatic chart can do.
Once you've got the habit, let an app take over the busywork if you like.
Day thirty: read the month like a mechanic reads an engine
Add up each bucket. Then ask three questions.
Where did I spend more than I thought? For most young men it's eating out. A lunch bought at work every day is a bill that never shows up as a bill. Don't treat the number as an accusation. Treat it as a reading on a gauge.
What did I spend on that I'd happily spend on again? Keep that. A budget with no room for anything enjoyable gets abandoned. If Friday night with your friends is worth $50 a week to you, write it in as a line item and spend it with a clear conscience.
What did the month cost that I'd forgotten about? Find the irregular items and divide them across the year. If car registration is $180 a year, that's $15 a month you should be setting aside whether the bill is due or not.
Build the budget from the real numbers
Now you can set limits you'll actually keep. Take the fixed bills as they are. Set food, car and fun just under what you really spent, and trim from the biggest leak first. Cutting a little from every bucket feels fair but changes nothing. Cutting one thing hard does.
Then do the move that separates men who build something from men who just get by. Pay yourself first. Set up an automatic transfer to a savings account for the day after payday, even if it's only $50. Money you never see in your checking account is money you can't talk yourself into spending. The first goal is a cushion that covers one month of your fixed bills, so a blown transmission or a missed shift is an inconvenience and not a disaster. What to do beyond that, whether it's paying down debt faster or investing, depends on your situation. Take that question to a fee-only financial planner or a banker at a credit union.
Where this goes wrong
You'll miss a day. Everybody does. You'll find a receipt in your jacket on Thursday for something from Monday. Write it down and keep going. The worst thing you can do is decide the whole month is ruined because day nine was sloppy. A month with three holes in it still teaches you more than a perfect plan you never started.
If you share a place, pay your share before anybody has to ask. Rent, utilities, the groceries you split. Leave the shared kitchen cleaner than you found it and nobody will be keeping a mental ledger on you. A roommate who has to chase you for $120 will remember it long after you've forgotten.
The move itself has its own costs, and a few of them hit in week one. Our piece on what moving out costs and what to do in the first month will help you prepare for those. And once your paychecks are steady, the first twelve months of earning, month by month shows where the money should go next.
The number you'll carry out of it
By day thirty you'll know something most men twice your age still don't: what it costs you to be you. Not what you hope it costs. What it does.
That number is the foundation of everything else. Write it on the first page of the notebook, and look at it before you buy the next thing.
Sam Ortiz
Dads & Family
Father of three. Writes about presence, discipline and the long game, without pretending any of it's tidy.
Watch
Worth an hour of your evening
More from Young Men.
From channels we rate. Plays on YouTube.
Read next