Quick answer: Wait for the official all-clear. Check for hazards from outside. Photograph and video everything before you move it. Stop further damage with temporary fixes and keep every receipt. Call your insurer the same day.
Picture the man who gets home after a storm, finds an inch of water in the kitchen, and spends the night dragging soaked carpet to the curb. He's tired and he wants to feel useful. Three days later the adjuster asks to see the carpet, the pad, and the water line on the drywall. All of it is in a pile by the road, and none of it is photographed.
Don't be him. The urge to clean is strong, and it's the first mistake. The order below protects your family first and your claim second.
Don't go back until they say you can
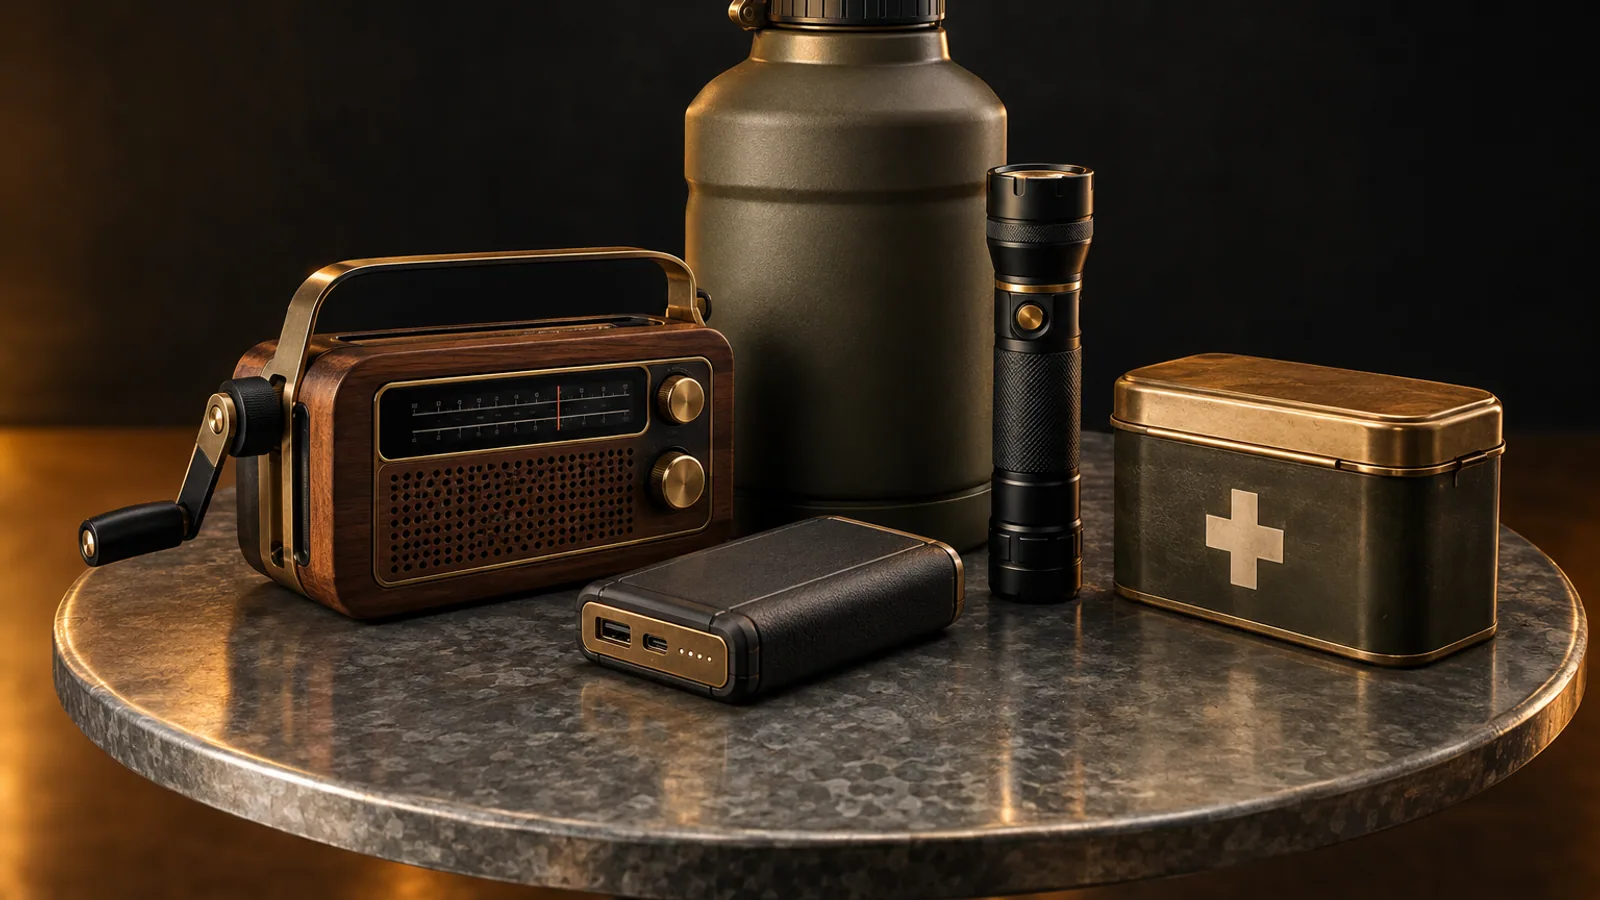
If there was an evacuation order, wait for local officials to lift it. Check your county emergency management page, local radio, or the sheriff's alerts. If the internet is down, a battery or hand-crank radio does the job (see When the Internet Goes Down, the Radio Still Works).
Roads are the first danger. The National Weather Service's rule is "Turn Around, Don't Drown." Six inches of fast-moving water can knock an adult off his feet. A foot can carry off a small car, and two feet can carry off most vehicles. You can't tell how deep it is, or whether the road underneath is still there. Take the long way around.
Go in daylight. Bring a second adult if you can, and tell someone where you're headed.
Walk the outside first
Before you open the door, walk the perimeter.
- Downed lines: Treat every one as live, including ones lying in a puddle or tangled in a tree. Stay far back and call the utility and 911.
- Gas: If you smell it or hear hissing, leave. Call from a safe distance. Don't flip a switch or flick a lighter.
- Structure: A sagging roofline, a leaning wall, a porch pulled away from the house, or a house knocked off its foundation means you don't go in. Wait for a building inspector.
- Water got inside: Leave the main breaker off, and don't touch electrical equipment while standing in water. Have an electrician check the system before you restore power.
Wear sturdy boots, long sleeves and work gloves. Add an N95 mask if there's dust or mold. Use a flashlight, never a candle. If you're running a generator, keep it well outside and far from windows. The rules are in Twenty Feet From the House and Other Generator Rules.
Photograph before you touch anything
This is the part that pays you back. Do it before you move one chair.
Start outside. Shoot all four sides of the house, the roof from the ground (don't climb up there), the fence, the vehicles, the trees that came down. Then go room by room.
For each room, take one wide shot from the doorway, then a slower pass of close-ups. Get the water line on the wall with a tape measure held against it. Get the cracked ceiling, the buckled floor, the ruined couch. Open the closets. Photograph the labels and serial numbers on appliances and electronics.
Then take a continuous video walk-through and talk as you go: the date, the room, what you see. It sounds silly, but it saves you from trying to remember in week three.
Annoying parts, said out loud:
- Power: Your phone battery will die halfway through. Bring a charged power bank.
- Light: A dark house makes useless photos. Bring a bright flashlight.
- Backup: Send the files to yourself by email or cloud the same day, so one dropped phone doesn't take them.
- Pre-storm records: If you have a home inventory video from before, find it now. If you don't, start one this month.
Start a running list of damaged belongings as you shoot: what it was, roughly when you bought it, what it cost. You'll be glad you wrote it down while it was in front of you.
Stop it from getting worse
Your policy almost certainly expects you to take reasonable steps to prevent more damage. Tarp the roof. Board the broken window. Shut off the water if a pipe burst. Keep receipts for every dollar, and keep the repairs temporary. Permanent work can wait until the insurer has seen it.
Wet materials are the tension. Photograph them, then deal with them quickly, because the EPA advises drying a water-damaged home within 24 to 48 hours to head off mold. Photograph first, pull second. If the adjuster can't come that fast, ask whether pictures and a few saved samples will do.
Food gets the same treatment. If the power was out long enough that the refrigerator rose above 40°F for two hours or more, the guidance is to throw out the perishables. Photograph them first, then toss them.
Call your insurer today
Use the number on your card or in the app. Ask for a claim number and write it on everything.
Then keep a notebook. Date, time, name of the person you spoke with, what they told you. You'll need it, and you'll be glad it exists if two people tell you two different things.
Ask these questions:
- What's my deductible for this type of loss? Some policies set a separate, higher one for wind or hurricanes.
- Does my policy pay for a hotel or rental if the house isn't livable? (This is often called loss of use or additional living expenses.)
- How do I submit receipts?
- When will an adjuster come?
One hard fact: standard homeowners policies generally don't cover flood damage. Flood coverage is a separate policy, often through the National Flood Insurance Program. If you have one, call that insurer too and ask about its deadlines.
I can't tell you what your policy covers. Your agent can, and so can your state department of insurance. If the claim turns into a dispute, talk to a licensed public adjuster or an attorney before you sign anything you don't understand.
Say no to the door-knockers
After a big storm, contractors show up with clipboards and quick deals. Some are honest. Some aren't, and you can't tell at the door.
Slow it down. Check the license with your state. Get written estimates, and don't hand over a large payment up front. Read carefully before signing anything that assigns your claim to someone else. It's fine to say "I'll call you." Anyone worth hiring will let you.
Know what else is out there
If the president has declared a disaster, FEMA assistance is available at disasterassistance.gov. File with your insurer first. FEMA can't duplicate what insurance pays.
Hotel nights, restaurant meals and a replacement phone charger add up fast, and reimbursement can be slow. That's where cash helps (Your Emergency Fund and the Cash You Can Actually Reach).
Then look next door
Once your own house is photographed, secured and reported, walk over to the neighbor's. Bring your gloves and a trash bag. The older couple on the corner may not be able to haul a downed limb, and a lot of folks won't ask.
Help them photograph before they start cleaning, too. You'll know what to say.
Ray Okonkwo
Money & Business
Former commercial banker turned small-business owner. Covers salary, credit, margins and the arithmetic nobody does before signing.
Watch
Worth an hour of your evening
More from Preparedness.
From channels we rate. Plays on YouTube.
Read next